 Coach
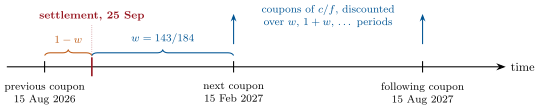
Between two coupon dates the seller of a bond has earned part of the next coupon, and the buyer pays it to her: this is accrued interest, under actual/actual, where is the fraction of the current period still to run. The dirty price (or full, or invoice price) is what changes hands; the clean price quoted on screens is the dirty price less accrued interest.
उदाहरण
Example 3.4 (Forty-one days)
A note paying 4.25% semiannually on 15 February and 15 August settles on 25 September 2026. The current period runs 184 days, of which 41 have elapsed: per 100, USD 4 735 per million, USD 47 351 on the trade of the opening paragraph.
Example 3.10 (The ten-year note)
At 4.200% the note of Example 3.4 has a clean price of 100.397405 (100-12+), a dirty price of 100.870911, a Macaulay duration of 8.142 years, a modified duration of 7.975, a DV01 of USD 804 per million and a convexity of 75.8. A 100-basis-point rise costs 7.675 points; duration alone predicts 8.044, duration and convexity together 7.662 (Figure 3.2).