
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Auction final price؟

Definition 23.8 Markets II: Rates, FX and Credit · الفصل 23 — Credit Default Swaps

The auction final price of a credit event is the price per 100 of par of the entity’s deliverable debt, set by the settlement auction, at which every CDS covered by the auction is cash settled and every physical settlement request made in the auction is executed.
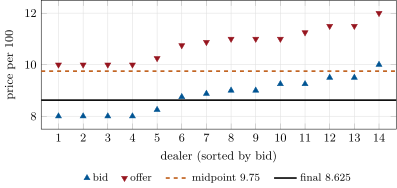
The first stage of the Lehman Brothers auction, 10 October 2008: each of the fourteen dealers’ bid and offer for USD 5 million of bonds. One pair crossed (a bid and an offer of 10); the average of the better half of the rest gave an inside market midpoint of 9.75. The open interest was USD 4.92 billion to sell, and the second stage set the final price at 8.625. Data: Helwege, Maurer, Sarkar and Wang, FRBNY Staff Report 372, Box 1.
Figure 23.4. The first stage of the Lehman Brothers auction, 10 October 2008: each of the fourteen dealers’ bid and offer for USD 5 million of bonds. One pair crossed (a bid and an offer of 10); the average of the better half of the rest gave an inside market midpoint of 9.75. The open interest was USD 4.92 billion to sell, and the second stage set the final price at 8.625. Data: Helwege, Maurer, Sarkar and Wang, FRBNY Staff Report 372, Box 1.

أمثلة

Example 23.9 (Lehman Brothers)

In the first stage, the highest bid, 10, met an offer of 10 and both were removed; the better seven of the remaining thirteen bids and offers averaged 9.804, rounded to 9.75. Requests to sell bonds totalled USD 5.69 billion and to buy USD 0.77 billion: an open interest of USD 4.92 billion to sell, capping the final price at 10.75. The dealer whose bid of 10 crossed, above the midpoint while the open interest was to sell, paid 5 million×(10−9.75)%=USD 12 5005\,\text{million} \times (10 - 9.75)\% = \text{USD}~12\,500. In the second stage, 453 bids to buy were submitted, from 10.75 down to 0.125; bids at 8.625 or higher added up to the open interest, and the final price was 8.625 (Figure 23.4).

اقرأ في الفصل →