Coach
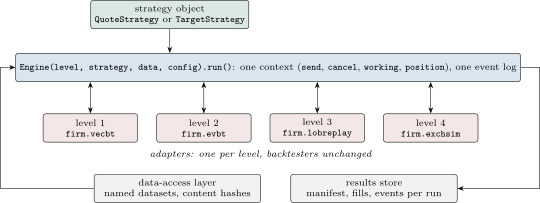
A backtest engine is the platform component that runs a strategy against historical or simulated markets at a chosen fidelity level through one strategy interface, reads its data through a data-access layer, records what the strategy saw and did in one event model, and stores every run with the identity of its code, data, parameters and seed.