جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Collateral choice option؟

Definition 2.10 Rates, Credit, XVA and Risk · الفصل 2 — Multi-Curve and Collateral Discounting

A collateral choice option is the right of the collateral poster to choose, and later change, which of several eligible collaterals it posts. Expressed in the trade’s currency, the poster chooses the collateral earning the highest rate, so the trade is discounted at max⁡ict(i)\max_i c^{(i)}_t over the eligible collaterals.

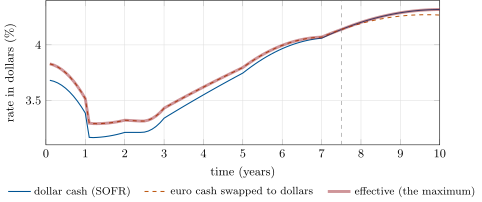
Instantaneous forward rates earned by two eligible collaterals, in dollars, and the effective discount rate when the poster may choose. The lines cross at 7.5 years (dashed), where the illustrative basis changes sign. Data: the chapter’s tutorial.
Figure 2.3. Instantaneous forward rates earned by two eligible collaterals, in dollars, and the effective discount rate when the poster may choose. The lines cross at 7.5 years (dashed), where the illustrative basis changes sign. Data: the chapter’s tutorial.

أمثلة

Example 2.11 (A dollar trade with a two-currency CSA)

Take an illustrative basis of −15-15 basis points at the front rising linearly to +5+5 at ten years. Euros are the better collateral until 7.5 years, dollars after. A payment of USD 100 million in ten years is worth USD 68 598 292 under a dollar-only CSA and USD 68 213 510 when the payer may post either currency: the choice, used at every date, raises the effective discount rate by an average of 56.25/10=5.656.25/10 = 5.6 basis points a year and costs the receiver USD 384 782. With volatile rates and basis the option is worth more than this intrinsic value.

اقرأ في الفصل →