Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Component share » ?

Definition 8.6 Microstructure and Execution · Chapitre 8 — Fragmentation and Routing

The component share of a market (Gonzalo and Granger, 1995) is its weight in the common permanent component, CSj=α⊥,j/∑kα⊥,k\mathrm{CS}_j=\alpha_{\perp,j}/\sum_k\alpha_{\perp,k}: large for a market that does not adjust to the others, which is to say for one that leads.
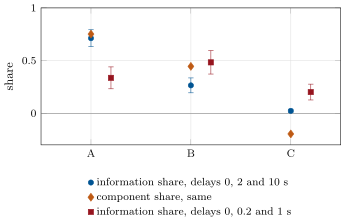
Price discovery on three simulated venues: information-share bounds (bars) and component shares, from one-second mid-quotes and five lags. With delays large enough to be seen at the sampling interval, both measures find the venue that learns first; with short delays they do not. Data: mx_frag.study.
Figure 8.3. Price discovery on three simulated venues: information-share bounds (bars) and component shares, from one-second mid-quotes and five lags. With delays large enough to be seen at the sampling interval, both measures find the venue that learns first; with short delays they do not. Data: mx_frag.study.
Lire dans le chapitre →
