Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Composite option?

Definition 17.16 Derivatives and Volatility · Capítulo 17 — Multi-Asset Options

A composite option is an option on the foreign asset’s value converted into the domestic currency at the prevailing rate, (STXT−K)+(S_TX_T-K)^+ with a domestic strike. Its underlying SXSX has volatility σS2+σX2+2ρσSσX\sqrt{\sigma_S^2+\sigma_X^2+2\rho\sigma_S\sigma_X}.

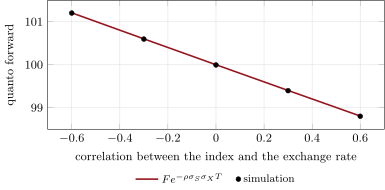
The one-year forward of a foreign index (forward 100, 20% volatility) paid at a fixed exchange rate whose volatility is 10%, by the correlation between the index and the rate. Data: the tutorial.
Figure 17.4. The one-year forward of a foreign index (forward 100, 20% volatility) paid at a fixed exchange rate whose volatility is 10%, by the correlation between the index and the rate. Data: the tutorial.
Leer en el capítulo →