
Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Credit factor?

Definition 19.1 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · Capítulo 19 — Systematic Credit and Bond-ETF Arbitrage

A credit factor is a characteristic of corporate bonds (spread against peers of similar rating and duration, recent spread change, duration or rating, issuer size) that sorts them into portfolios whose returns in excess of Treasuries differ persistently, after adjusting for their spread duration.
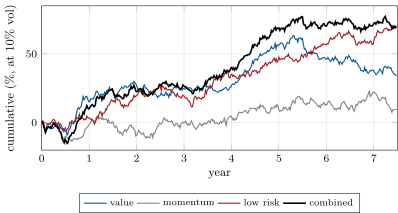
Three synthetic credit factor books and their equal-risk combination, each scaled to 10% volatility, cumulative sums of daily returns. Data: s2_syscredit.market.
Figure 19.1. Three synthetic credit factor books and their equal-risk combination, each scaled to 10% volatility, cumulative sums of daily returns. Data: s2_syscredit.market.
Leer en el capítulo →