 Coach
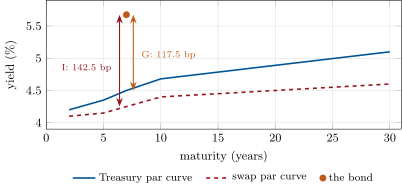
A credit spread is the extra yield a risky bond pays over a reference curve. The G-spread is the bond’s yield minus the government yield interpolated at its maturity; the I-spread its yield minus the interpolated swap rate. The Z-spread is the constant spread which, added to the swap zero curve, discounts the bond’s cash flows to its price. The asset-swap spread is the spread over the floating rate that a buyer of the bond earns by swapping its fixed coupons into floating payments, at par: the difference between the bond’s value on the swap curve and its price, divided by the annuity of the floating leg.
Examples
Example 21.5 (One bond, four spreads)
A seven-year corporate bond pays a 5.50% semiannual coupon and trades at 99.00: its yield is 5.6751%. With the illustrative curves of Figure 21.2, the seven-year Treasury at 4.50% and swap at 4.25%, its G-spread is 117.5 basis points and its I-spread 142.5. Its Z-spread over the swap zero curve is 140.7 basis points and its asset-swap spread 142.9.