
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Discounting switch » ?

Definition 2.12 Rates, Credit, XVA and Risk · Chapitre 2 — Multi-Curve and Collateral Discounting

A discounting switch is a change of the collateral rate of a population of trades, and hence of their discount curve, on a set date, with the resulting changes in value compensated in cash and, where required, the changes in risk compensated with basis swaps.
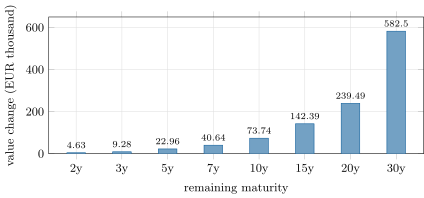
Gain at the euro discounting switch of a receiver of 1.50% against six-month Euribor on EUR 100 million, by remaining maturity, on illustrative curves of July 2020 (euro swap rates between -0.50\% and +0.08\%). The clearing house’s cash compensation took each gain back. Data: the chapter’s tutorial.
Figure 2.4. Gain at the euro discounting switch of a receiver of 1.50% against six-month Euribor on EUR 100 million, by remaining maturity, on illustrative curves of July 2020 (euro swap rates between −0.50%-0.50\% and +0.08%+0.08\%). The clearing house’s cash compensation took each gain back. Data: the chapter’s tutorial.
Lire dans le chapitre →