
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Dividend risk and dividend swap » ?

Aussi appelé : dividend risk · dividend swap

Definition 5.10 Derivatives and Volatility · Chapitre 5 — Dividends, Borrow and Forwards

Dividend risk is the sensitivity of a position to a change in the dividends expected before its maturity: a forward, a long call or a short put loses when expected dividends rise. A dividend swap is an over-the-counter contract that exchanges, at maturity, the dividends actually paid on a share or index over a period for a fixed amount agreed at inception; the listed version is the dividend future of One Quant Book 1, chapter 22.
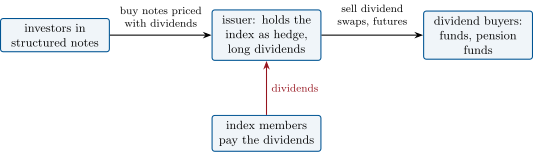
Where dividend risk goes. The issuer of equity-linked notes hedges with the underlying, is paid its dividends and has promised their expected value to the note holders; it lays the risk off by selling dividends forward to investors who want them.
Figure 5.4. Where dividend risk goes. The issuer of equity-linked notes hedges with the underlying, is paid its dividends and has promised their expected value to the note holders; it lays the risk off by selling dividends forward to investors who want them.
Lire dans le chapitre →