 Coach
The equity-implied spread of a company is the credit default swap spread that a structural model gives from its share price, equity volatility and debt per share; comparing it with the market spread measures whether the equity and credit markets disagree about the company’s default risk.
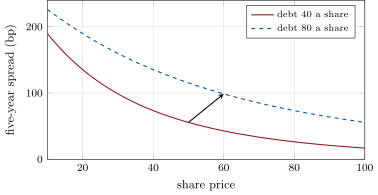
s2_capstruct.curve.