सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Implied dividend and implied borrow rate क्या है?

अन्य नाम: implied dividend · implied borrow rate

Definition 5.8 Derivatives and Volatility · अध्याय 5 — Dividends, Borrow and Forwards

The implied dividend of an expiry is the present value of dividends to that expiry that makes the forward read from options, together with the known borrow cost, consistent with the spot. The implied borrow rate is the borrow fee ℓ\ell that makes the forward consistent with the spot and a dividend forecast: ℓ=−ln⁡(FP(0,T)/(S−Dˉ))/T\ell=-\ln\bigl(FP(0,T)/(S-\bar D)\bigr)/T.

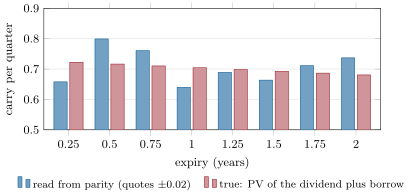
Present value of the carry (dividend plus borrow cost) between consecutive quarterly expiries, recovered by the parity regression from a synthetic chain whose mid prices carry up to two cents of noise at nine strikes. The cumulative forward is recovered to about a cent; each quarter’s increment only to about 0.08. Data: the tutorial.
Figure 5.3. Present value of the carry (dividend plus borrow cost) between consecutive quarterly expiries, recovered by the parity regression from a synthetic chain whose mid prices carry up to two cents of noise at nine strikes. The cumulative forward is recovered to about a cent; each quarter’s increment only to about 0.08. Data: the tutorial.

उदाहरण

Example 5.9 (The hard-to-borrow share)

The one-month chain of the opening, five strikes from 45 to 55 quoted to the cent, regressed as in Method 5.7, gives a forward of 48.74 and a discount factor of 0.99680 (a rate of 3.90%, against 4% true: the cents of rounding). With no dividend due, the carry of 1.42 is all borrow: 35.0% a year. Priced from the naive forward 50e0.04×30/365=50.1650e^{0.04\times30/365}=50.16 at the chain’s 60% volatility, the call would be worth 3.50 instead of 2.78, and the put 3.34 instead of 4.04. The “skew” of 72 against 47 is the wrong forward, not the market’s view of volatility.

अध्याय में पढ़ें →