All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Inverse option?

Definition 19.4 Markets III: Commodities, Energy and Crypto · Chapter 19 — Dated Futures, Options and ETFs

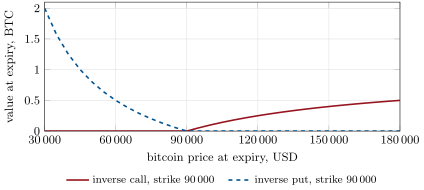
An inverse option is a European option on the dollar price of a coin whose premium is quoted and paid in the coin and whose payoff is settled in the coin: a call pays (FT−K)+/FT(F_T - K)^+/F_T coins at expiry, where FTF_T is the settlement price and KK the strike in dollars.

Value in bitcoin at expiry of inverse options struck at 90 000 (): the call’s coin value approaches but never reaches one bitcoin; the put’s grows without bound as the price falls. In dollars both are the ordinary payoffs. Data: the chapter’s tutorial.
Figure 19.1. Value in bitcoin at expiry of inverse options struck at 90 000 (Proposition 19.5): the call’s coin value approaches but never reaches one bitcoin; the put’s grows without bound as the price falls. In dollars both are the ordinary payoffs. Data: the chapter’s tutorial.
Deltas of December 2026 inverse calls across strikes, at the venue’s marked volatilities of . Deep in the money the premium-adjusted delta falls: the premium, paid in bitcoin, is itself a large bitcoin exposure, and the 60 000 call’s adjusted delta (0.645) is below the 70 000 call’s (0.658). Data: the chapter’s tutorial.
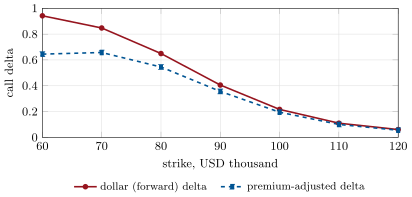
Figure 19.2. Deltas of December 2026 inverse calls across strikes, at the venue’s marked volatilities of Box 19.3. Deep in the money the premium-adjusted delta falls: the premium, paid in bitcoin, is itself a large bitcoin exposure, and the 60 000 call’s adjusted delta (0.645) is below the 70 000 call’s (0.658). Data: the chapter’s tutorial.
Read in context →