
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Net open position limit, settlement limit؟

يُعرف أيضًا باسم: net open position limit · settlement limit

Definition 27.3 Markets II: Rates, FX and Credit · الفصل 27 — Getting Access: FX

A net open position limit caps the client’s net currency exposure through the prime broker, measured in one currency across all currencies. A settlement limit caps, for each value date, the amount the prime broker will have to settle on the client’s trades.
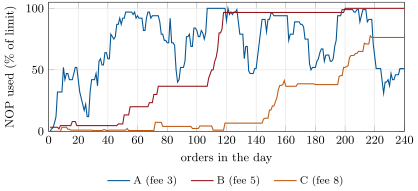
A simulated day of 240 orders routed by the gate to the cheapest prime broker whose limits allow them: the net open position at each, in per cent of its limit. A fills first, from order 107 the flow that adds to the position spills to B, and then to C, whose position ends the day at 76% of its limit. No order is rejected. Illustrative; data: the chapter’s tutorial, seeded.
Figure 27.3. A simulated day of 240 orders routed by the gate to the cheapest prime broker whose limits allow them: the net open position at each, in per cent of its limit. A fills first, from order 107 the flow that adds to the position spills to B, and then to C, whose position ends the day at 76% of its limit. No order is rejected. Illustrative; data: the chapter’s tutorial, seeded.

أمثلة

Example 27.4 (Two trades through the gate)

Prime broker A allows EURUSD and USDJPY up to seven days, a net open position of USD 100 million and settlement of USD 500 million per value date. The fund buys EUR 50 million at 1.10 for spot: it is long EUR worth USD 55 million and short USD 55 million, a net open position of 55 million and a settlement amount of 55 million. It then buys USD 20 million against yen: the dollar short shrinks to 35 million and a yen short of 20 million appears; the longs are still the 55 million of euros, and so is the settlement amount. A further purchase of EUR 95 million would take the position to 159.5 million and is rejected; a sale of euros would be accepted even if the limit had been cut below the position, because it reduces it.

اقرأ في الفصل →