 المدرب
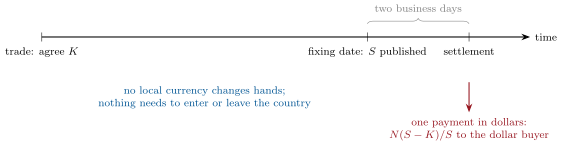
A non-deliverable forward (NDF) is a forward on a currency pair that is settled in cash, in dollars, for the difference between the contract rate and a published fixing rate on a fixing date: on a dollar notional , the dollar buyer receives . The fixing source is the rate the contract names for , usually a rate published by the local central bank or an official agent.
| Currency | Fixing source (EMTA code) | Published by, around |
|---|---|---|
| Indian rupee | INR FBIL | Financial Benchmarks India, 13:30 Mumbai |
| Brazilian real | BRL PTAX | Banco Central do Brasil, 13:15 São Paulo |
| Chinese renminbi | CNY SAEC | CFETS for the People’s Bank, 9:15 Beijing |
| Korean won | KRW KFTC18 | Seoul Money Brokerage, 16:00 Seoul |
| Taiwan dollar | TWD TAIFX1 | Taipei Forex, 11:00 Taipei |
أمثلة
Example 18.5 (A won NDF)
A fund buys USD 10 million three months forward against won in an NDF at 1 380.00, settling on Tuesday 13 October 2026. The fixing is taken two business days before, on Friday 9 October, at 1 425.50: the fund receives . Had the won fixed at 1 350.00, the fund would have paid USD 222 222.