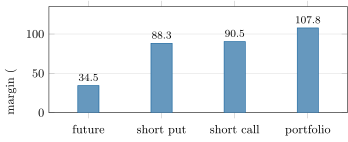
Portfolio margining sets the requirement on the net risk of all positions in an account, recognising offsets between them, in contrast with a sum of requirements computed position by position.
 Coach
Log in
Start reading
Quantitative Finance · Glossary
Portfolio margining sets the requirement on the net risk of all positions in an account, recognising offsets between them, in contrast with a sum of requirements computed position by position.