
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Quality option and wildcard option؟

يُعرف أيضًا باسم: quality option · wildcard option

Definition 6.9 Markets II: Rates, FX and Credit · الفصل 6 — Bond Futures

The short’s right to choose which note to deliver is the quality option. The wildcard option is its right, during the delivery period, to decide whether to deliver after the futures settlement price has been fixed for the day, while the notes still trade; after the last trading day the invoice price is fixed and the short may deliver on any of the remaining days. The right to choose the day within the delivery month is the timing option.
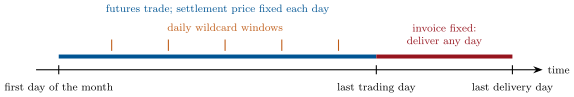
The delivery month of the ten-year note future. The short chooses the note (quality option), the day (timing option), and, every day until trading stops, whether to deliver after the day’s settlement price is known (wildcard option). Trading stops on the seventh business day before the last business day of the month; the invoice price is then fixed, and delivery may take place on any remaining business day up to the last.
Figure 6.2. The delivery month of the ten-year note future. The short chooses the note (quality option), the day (timing option), and, every day until trading stops, whether to deliver after the day’s settlement price is known (wildcard option). Trading stops on the seventh business day before the last business day of the month; the invoice price is then fixed, and delivery may take place on any remaining business day up to the last.
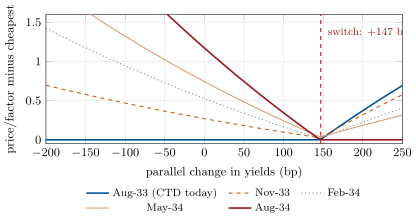
At delivery, each note’s clean price divided by its factor, minus the lowest, as all yields move together. The note on zero is the CTD. From today’s yields the shortest note stays cheapest until yields have risen 147 basis points, to about 5.5%; beyond that the longest note takes over. Notes and yields are illustrative. Data: the chapter’s tutorial.
Figure 6.3. At delivery, each note’s clean price divided by its factor, minus the lowest, as all yields move together. The note on zero is the CTD. From today’s yields the shortest note stays cheapest until yields have risen 147 basis points, to about 5.5%; beyond that the longest note takes over. Notes and yields are illustrative. Data: the chapter’s tutorial.
اقرأ في الفصل →