
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Spot return, roll yield, collateral return क्या है?

अन्य नाम: spot return · roll yield · collateral return

Definition 10.7 Markets III: Commodities, Energy and Crypto · अध्याय 10 — Forward Curves, Storage and Convenience Yield

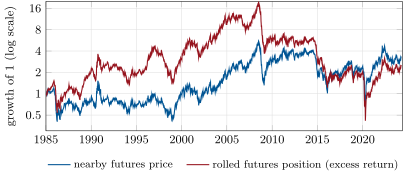
For a fully collateralised, rolled long futures position, the spot return is the change in the nearby futures price; the roll yield is the rest of the futures’ return, earned as each held contract converges to the nearby price (positive in backwardation, negative in contango); the collateral return is the interest earned on the cash that backs the position. Their sum is the total return.
WTI, January 1985 to April 2024: the nearby price and a long position rolled monthly over the 5th–9th trading days, both starting at 1. The gap is the cumulative roll yield. Contract identities follow the expiry rule with a weekend-only calendar, so a few roll dates may be off by a day. Data: EIA contracts 1–4.
Figure 10.3. WTI, January 1985 to April 2024: the nearby price and a long position rolled monthly over the 5th–9th trading days, both starting at 1. The gap is the cumulative roll yield. Contract identities follow the expiry rule with a weekend-only calendar, so a few roll dates may be off by a day. Data: EIA contracts 1–4.
अध्याय में पढ़ें →