
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Spot value date, cross rate؟

يُعرف أيضًا باسم: spot value date · cross rate

Definition 14.2 Markets II: Rates, FX and Credit · الفصل 14 — The FX Market

The spot value date of a trade is the day on which the two currencies are exchanged: by convention the second business day after the trade, counting only days that are business days in both currencies, and the first for dollar–Canadian dollar. A cross rate is the rate between two currencies neither of which is the dollar, such as EURJPY, traded directly or through the two dollar pairs.
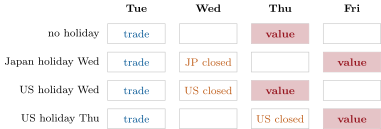
Spot value dates of a dollar–yen trade done on a Tuesday. A Japanese holiday on the intermediate day pushes settlement to Friday; a US holiday on it does not; a US holiday on the value date itself does. The rule as described by Federal Reserve economists in 2003; holidays hypothetical.
Figure 14.1. Spot value dates of a dollar–yen trade done on a Tuesday. A Japanese holiday on the intermediate day pushes settlement to Friday; a US holiday on it does not; a US holiday on the value date itself does. The rule as described by Federal Reserve economists in 2003; holidays hypothetical.

أمثلة

Example 14.4 (Three crosses)

With EURUSD 1.1462/1.1464, USDJPY 156.86/156.88 and GBPUSD 1.3371/1.3373, the synthetic EURJPY is 179.7929/179.8472, 5.43 pips wide, a relative spread of 3.02 basis points against 1.74 and 1.27 for the legs; EURGBP is 0.85710/0.85738, 2.78 pips; GBPJPY 209.7375/209.7956, 5.81 pips. A dealer that quotes a cross directly can quote it tighter than the synthetic, but not crossed with it: a direct EURJPY bid above 179.8472 could be sold to and bought back through the legs at a profit.

اقرأ في الفصل →