
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Spread mean reversion » ?

Definition 21.3 Strategies I: Equities and Futures · Chapitre 21 — Calendar Spreads and Curve Trades

Spread mean reversion is the tendency of a spread between related prices to return toward a normal level after a deviation; a spread mean-reversion strategy sells the spread when it is high relative to its recent mean and buys it when it is low.
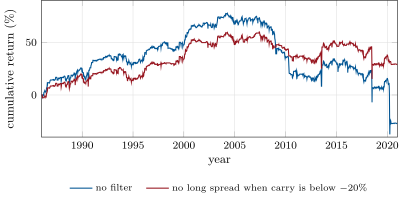
The WTI calendar-spread mean-reversion rule after costs, 1986–2020, at a 10% volatility target: cumulative sum of daily returns, without a storage filter and with the filter that turns out best in hindsight. Data: s1_curve.book.
Figure 21.1. The WTI calendar-spread mean-reversion rule after costs, 1986–2020, at a 10% volatility target: cumulative sum of daily returns, without a storage filter and with the filter that turns out best in hindsight. Data: s1_curve.book.
Lire dans le chapitre →