Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Timing adjustment » ?

Definition 6.1 Rates, Credit, XVA and Risk · Chapitre 6 — Convexity Adjustments and Constant-Maturity Products

The timing adjustment of a rate paid at a date TpT_p other than its natural payment date is ETp[Fk(Tk−1)]−Fk(0)\E^{T_p}[F_k(T_{k-1})]-F_k(0): the difference between its expectation under the TpT_p-forward measure and its forward.

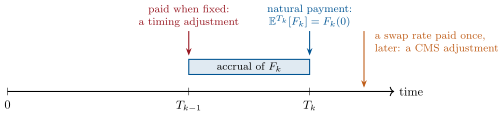
Where a rate is paid decides the measure of its expectation. Paid at the end of its accrual period, a forward rate needs no adjustment; paid at its fixing, it needs a timing adjustment; a swap rate paid once, on a single date, needs a constant-maturity adjustment.
Figure 6.1. Where a rate is paid decides the measure of its expectation. Paid at the end of its accrual period, a forward rate needs no adjustment; paid at its fixing, it needs a timing adjustment; a swap rate paid once, on a single date, needs a constant-maturity adjustment.
Lire dans le chapitre →