 Pelatih
The vanna–volga method prices an option as its Black price at the at-the-money volatility plus the smile cost of a portfolio of the three quoted instruments (25-delta put, at-the-money, 25-delta call) that matches the option’s vega, vanna and volga (chapter 4), all computed at the at-the-money volatility.
Contoh
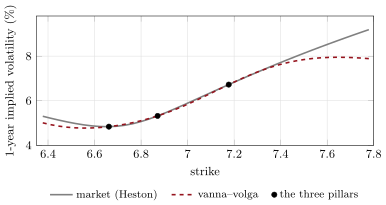
Example 20.4 (Vanna–volga against the true smile)
Built from the three 25-delta pillars of Example 20.2, the vanna–volga smile matches the market to a few hundredths of a point between the pillars. At the 10-delta call strike it gives 7.94% against the market’s 8.91%, a point low (Figure 20.1). The 10-delta quotes carry information that the three pillars do not.