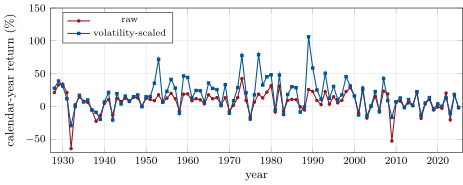
Volatility-scaled momentum holds a momentum portfolio with a weight inversely proportional to the strategy’s own recent realised volatility, so that its forecast volatility is constant; the weight is recomputed each period from data before it.
 Coach
Inloggen
Begin met lezen
Quantitative Finance · Begrippenlijst
Volatility-scaled momentum holds a momentum portfolio with a weight inversely proportional to the strategy’s own recent realised volatility, so that its forecast volatility is constant; the weight is recomputed each period from data before it.