
Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Worst-case exposure?

Definition 22.2 Low-Latency Software · Capítulo 22 — Pre-Trade Risk and Kill Switches

The worst-case exposure of a firm in an instrument is its position plus everything its open orders could still add if they all filled: on the long side, the position plus the remaining quantity of every open buy order, including those whose acknowledgement or cancellation has not arrived; on the short side, the same with sell orders. A limit is respected in the worst case if a new order fits under it on top of this exposure.
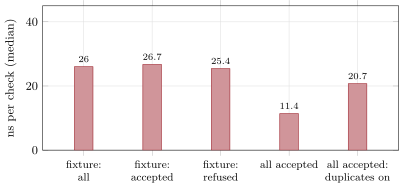
The cost of one pass through the gate’s twelve checks, median of TSC-timed calls: on the fixture’s 4 874 orders (every kind of refusal, cold tables), split by outcome; and on a stream where every order passes, with the duplicate check off and on. Measured on a laptop (Intel Core Ultra 7 155H) under WSL2. Data: bench_risk.py.
Figure 22.2. The cost of one pass through the gate’s twelve checks, median of TSC-timed calls: on the fixture’s 4 874 orders (every kind of refusal, cold tables), split by outcome; and on a stream where every order passes, with the duplicate check off and on. Measured on a laptop (Intel Core Ultra 7 155H) under WSL2. Data: bench_risk.py.
Leer en el capítulo →