
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Adjustment factor؟

Definition 8.10 Markets I: The Ecosystem and Exchange-Traded Markets · الفصل 8 — Shares, Corporate Actions and Indices

The adjustment factor of a corporate action is the number ff by which every price before its ex-date is multiplied so that the adjusted series has no jump caused by the action. A back-adjusted price is the raw price times the product of the factors of all later actions.
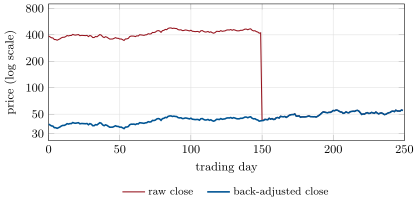
A simulated stock with a ten-for-one split on day 150 and dividends on days 60 and 200. The raw series shows a 90% fall that no holder experienced; the back-adjusted series is continuous, and all its values before day 200 differ from the prices that actually traded. Data: the chapter’s script.
Figure 8.2. A simulated stock with a ten-for-one split on day 150 and dividends on days 60 and 200. The raw series shows a 90% fall that no holder experienced; the back-adjusted series is continuous, and all its values before day 200 differ from the prices that actually traded. Data: the chapter’s script.

أمثلة

Example 8.13 (Two basis points)

P=102P = 102, D=2D = 2, and the stock closes ex at 99, a 1% fall net of the dividend. The standard factor gives −1.000%-1.000\%; the holder earned 101/102−1=−0.980%101/102 - 1 = -0.980\%. The error, two basis points, is εD/P\varepsilon D/P. Vendors differ in which factor they publish: two “adjusted close” series for the same stock need not agree, and a research database must state its convention.

اقرأ في الفصل →