 Coach
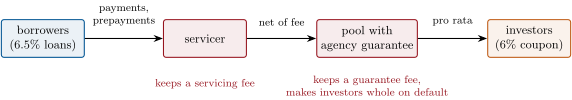
An agency mortgage-backed security is a security backed by a pool of residential mortgages whose timely payment of interest and principal is guaranteed by a government-sponsored enterprise (Fannie Mae, Freddie Mac) or by a government agency (Ginnie Mae, whose guarantee carries the full faith and credit of the United States). The basic form is the pass-through: each month it passes the borrowers’ payments, interest at the pool’s coupon and all principal, scheduled and prepaid, to the investors pro rata, after the servicer and the guarantor have taken their fees.
Ejemplos
Example 12.3 (A new pool)
USD 100 million of new thirty-year 6.5% loans back a 6% pass-through. The level monthly payment is USD 632 068; in the first month it contains USD 541 667 of interest and USD 90 401 of scheduled principal, and at 100% PSA (a CPR of 0.2%) USD 16 667 is prepaid. Investors receive USD 500 000 of interest, the 6% coupon, and all USD 107 068 of principal. The weighted average life, the average time to the return of a dollar of principal, is 19.6 years with no prepayment, 11.5 at 100% PSA and 5.8 at 300%.