 Coach
For fixed-leg payment dates with accrual fractions and discount factors , the annuity is , the value of receiving 1 a year on the fixed leg’s schedule. The par swap rate is the fixed rate at which the swap is worth zero at inception.
Examples
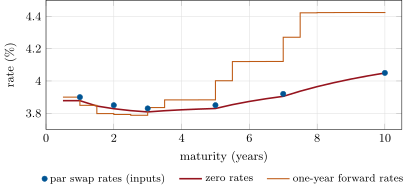
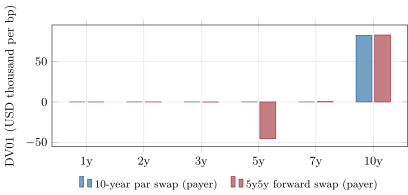
Example 9.8 (A ten-year swap)
With illustrative par rates of 3.90, 3.85, 3.83, 3.85, 3.92 and 4.05% at one, two, three, five, seven and ten years, the ten-year par rate is 4.05% by construction, the annuity is 8.228 and the swap’s DV01 on USD 100 million is USD 82 278 by , and USD 82 262 when the curve is rebuilt after bumping each input by a basis point. All of it falls on the ten-year pillar: a par swap is hedged exactly by the swap that built its pillar.