
Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Annuity and par swap rate?

Também chamado de: annuity · par swap rate

Definition 9.5 Markets II: Rates, FX and Credit · Capítulo 9 — Interest-Rate Swaps

For fixed-leg payment dates t1,…,tnt_1, \dots, t_n with accrual fractions δi\delta_i and discount factors P(ti)P(t_i), the annuity is A=∑iδiP(ti)A = \sum_i \delta_i P(t_i), the value of receiving 1 a year on the fixed leg’s schedule. The par swap rate is the fixed rate at which the swap is worth zero at inception.
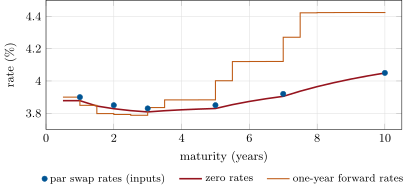
The curve bootstrapped from six illustrative par rates. Zero rates are smooth; forward rates are flat between pillars and jump at them, an artefact of interpolating the logarithm of discount factors linearly: every choice of interpolation is a choice of forward curve, and One Quant Book 6 treats better ones. Data: the chapter’s tutorial.
Figure 9.2. The curve bootstrapped from six illustrative par rates. Zero rates are smooth; forward rates are flat between pillars and jump at them, an artefact of interpolating the logarithm of discount factors linearly: every choice of interpolation is a choice of forward curve, and One Quant Book 6 treats better ones. Data: the chapter’s tutorial.
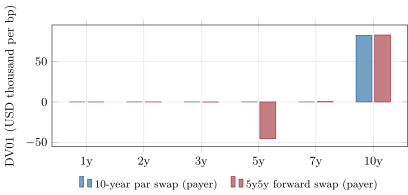
Bucketed DV01 of two payer swaps of USD 100 million: the change in value when each input par rate rises by a basis point and the curve is rebuilt. The par ten-year loads only its own pillar. The five-year swap starting in five years is long ten-year rates and short five-year rates: it is a bet on the forward, and its hedge is a pair of par swaps. Data: the chapter’s tutorial.
Figure 9.3. Bucketed DV01 of two payer swaps of USD 100 million: the change in value when each input par rate rises by a basis point and the curve is rebuilt. The par ten-year loads only its own pillar. The five-year swap starting in five years is long ten-year rates and short five-year rates: it is a bet on the forward, and its hedge is a pair of par swaps. Data: the chapter’s tutorial.

Exemplos

Example 9.8 (A ten-year swap)

With illustrative par rates of 3.90, 3.85, 3.83, 3.85, 3.92 and 4.05% at one, two, three, five, seven and ten years, the ten-year par rate is 4.05% by construction, the annuity is 8.228 and the swap’s DV01 on USD 100 million is USD 82 278 by NA×10−4N A \times 10^{-4}, and USD 82 262 when the curve is rebuilt after bumping each input by a basis point. All of it falls on the ten-year pillar: a par swap is hedged exactly by the swap that built its pillar.

Ler no capítulo →