सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

At-the-money क्या है?

Definition 25.4 Markets I: The Ecosystem and Exchange-Traded Markets · अध्याय 25 — Volatility as a Traded Quantity: First Contact

An option is at-the-money when its strike equals the forward (or, loosely, the spot). Its price is, to a good approximation, proportional to volatility: CATM≈0.4 F e−rTσTC_{\text{ATM}} \approx 0.4\,F\,\mathrm{e}^{-rT}\sigma\sqrt{T}.

Price against volatility for two three-month options on a share at 100 with a forward of 100.20. Inverting the curve at the market price gives the implied volatility: 4.06 is 20.1 for the call, 1.12 is 23.8 for the put. Near the money the curve is a straight line; far from it, it is flat at low volatility, which is where solvers lose precision. Data: the chapter’s build.
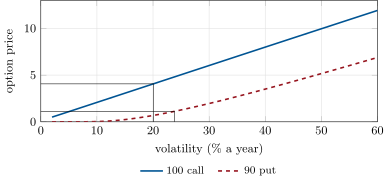
Figure 25.1. Price against volatility for two three-month options on a share at 100 with a forward of 100.20. Inverting the curve at the market price gives the implied volatility: 4.06 is 20.1 for the call, 1.12 is 23.8 for the put. Near the money the curve is a straight line; far from it, it is flat at low volatility, which is where solvers lose precision. Data: the chapter’s build.
अध्याय में पढ़ें →