Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Barrier shift?

Definition 15.12 Derivatives and Volatility · Capítulo 15 — Barriers and Digitals

The barrier shift prices an option monitored every Δt\Delta t with the continuous formula at the barrier H e±βσΔtH\,e^{\pm\beta\sigma\sqrt{\Delta t}}, moved away from the spot, with β≈0.5826\beta\approx0.5826.

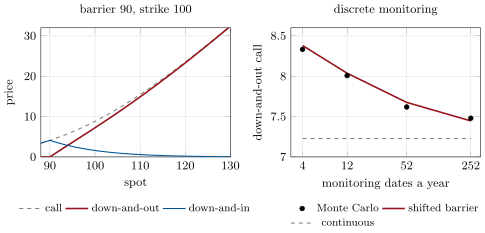
Left: a call, its down-and-out and its down-and-in by spot (one year, 20%); they add up. Right: the down-and-out call monitored 4, 12, 52 and 252 times a year: Monte Carlo against the continuous formula and the formula at the shifted barrier. Data: the tutorial.
Figure 15.3. Left: a call, its down-and-out and its down-and-in by spot (one year, 20%); they add up. Right: the down-and-out call monitored 4, 12, 52 and 252 times a year: Monte Carlo against the continuous formula and the formula at the shifted barrier. Data: the tutorial.

Ejemplos

Example 15.13 (How good is the shift)

The knock-out call of Example 15.9 (barrier 90) is worth 7.23 with continuous monitoring. With daily monitoring, a Monte Carlo of 200 000 paths gives 7.48 (standard error 0.03), and the shifted formula 7.45. With weekly monitoring they give 7.62 and 7.68, with monthly 8.01 and 8.04, and with four dates 8.33 and 8.38 (Figure 15.3, right). For an up-and-out call with barrier 120, where the payoff is large at the barrier, the shift is good daily (1.26 against 1.28) and poor quarterly (2.19 against 2.50). The correction is an expansion in Δt\sqrt{\Delta t} and fails when the barrier is within a few steps of the spot or the payoff at the barrier is large.

Leer en el capítulo →