Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Bates model?

Definition 13.4 Derivatives and Volatility · Capítulo 13 — Jumps and Lévy Models

The Bates model is Heston’s stochastic volatility model (chapter 10) with Merton jumps added to the price. The characteristic function is the product of Heston’s and the jump factor, and the parameters are (v0,κ,vˉ,η,ρ,λ,μJ,δ)(v_0,\kappa,\bar v,\eta,\rho,\lambda,\mu_J,\delta).

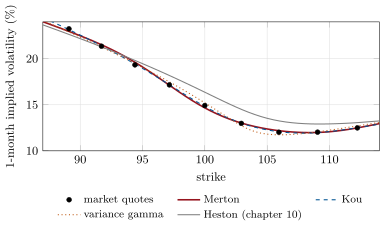
One-month smiles of chapter 9’s surface: the nine fitted quotes, the three jump models fitted to them, and Heston calibrated to the whole surface. On one expiry every jump model fits; the differences appear at other expiries. Data: the tutorial.
Figure 13.2. One-month smiles of chapter 9’s surface: the nine fitted quotes, the three jump models fitted to them, and Heston calibrated to the whole surface. On one expiry every jump model fits; the differences appear at other expiries. Data: the tutorial.

Exemplos

Example 13.5 (Three models on one expiry, one on all)

Fitted to the one-month smile of chapter 9’s surface (nine strikes within two standard moves), Merton returns σ=9.8%\sigma=9.8\%, λ=3.16\lambda=3.16, μJ=−5.8%\mu_J=-5.8\%, δ=4.6%\delta=4.6\% with a root-mean-square error of 0.18 volatility point. Kou returns σ=8.4%\sigma=8.4\%, λ=11.7\lambda=11.7, p=0.24p=0.24, η1=85\eta_1=85, η2=30.4\eta_2=30.4, with an error of 0.06. Variance gamma (next section) has an error of 0.24 (Figure 13.2). Carried to other expiries, all three fail. At one year Merton’s skew is −0.07-0.07 against the market’s −0.25-0.25. At one week variance gamma’s is −3.66-3.66 against −1.44-1.44 (Figure 13.1). Bates fitted to all eight expiries from one week to two years has an error of 0.34 point, with v0=0.018v_0=0.018, κ=2.06\kappa=2.06, vˉ=0.062\bar v=0.062, η=0.85\eta=0.85, ρ=−0.70\rho=-0.70 and jumps λ=2.34\lambda=2.34, μJ=−3.6%\mu_J=-3.6\%, δ=3.0%\delta=3.0\%. Its skew is −1.36-1.36 at one week and −0.23-0.23 at one year.

Ler no capítulo →