
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Benchmark fix, fixing window, fixing order؟

يُعرف أيضًا باسم: benchmark fix · fixing window · fixing order

Definition 17.1 Markets II: Rates, FX and Credit · الفصل 17 — Fixings and Flows

A benchmark fix is an exchange rate published at a set time of day by an administrator, from trades and quotes observed in a short period around that time, the fixing window. A fixing order is a client’s order to buy or sell an amount of currency at the fix, whatever it turns out to be; the dealer that accepts it guarantees the rate and bears the cost of obtaining it.
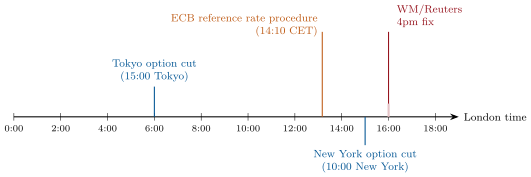
The day’s reference moments in London time, in winter. The WM/Reuters fix is taken over five minutes around 16:00; the ECB’s reference rates come from a procedure around 14:10 Central European time; FX options expire most often at 10:00 New York or 15:00 Tokyo. The clocks of summer time shift some of them by an hour. Schematic.
Figure 17.1. The day’s reference moments in London time, in winter. The WM/Reuters fix is taken over five minutes around 16:00; the ECB’s reference rates come from a procedure around 14:10 Central European time; FX options expire most often at 10:00 New York or 15:00 Tokyo. The clocks of summer time shift some of them by an hour. Schematic.
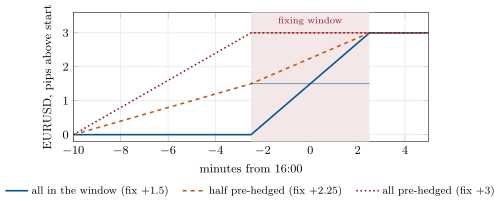
The price of EURUSD while a dealer buys EUR 1 billion for a client’s fixing order, with a permanent impact of 0.3 pips per EUR 100 million, when it buys all of it in the five-minute window, half before, or all before. The thin lines mark the fix in the first and last cases. The dealer’s average cost is 1.5 pips in each case; the fix is not. Illustrative; data: the chapter’s tutorial.
Figure 17.2. The price of EURUSD while a dealer buys EUR 1 billion for a client’s fixing order, with a permanent impact of 0.3 pips per EUR 100 million, when it buys all of it in the five-minute window, half before, or all before. The thin lines mark the fix in the first and last cases. The dealer’s average cost is 1.5 pips in each case; the fix is not. Illustrative; data: the chapter’s tutorial.

أمثلة

Example 17.3 (A billion euros at the fix)

With λ=0.3\lambda = 0.3 pips per EUR 100 million, buying EUR 1 billion moves the price 3 pips. Bought evenly in the window, the fix is 1.5 pips above the start and the dealer’s average cost is the same. Half bought before the window, the fix is 2.25 pips up and the dealer earns 0.75 pips on EUR 1 billion, USD 75 000; all before, USD 150 000. The client pays the same amounts more than with no pre-hedging.

اقرأ في الفصل →