 Coach
The bond floor of a convertible is the value of the same bond without the conversion right: its coupons and principal discounted for the issuer’s credit (Book 2, chapter 21).
Exemplos
Example 21.8 (The convertible across share prices)
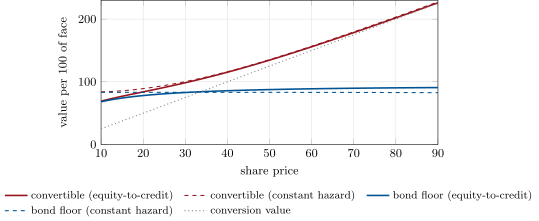
Under a constant 5% hazard, the convertible is worth 89.1, 100.2, 116.0, 156.7 and 203.2 at share prices of 20, 30, 40, 60 and 80. Its bond floor is 83.2 throughout. The conversion values are 50, 75, 100, 150 and 200, so the conversion premium falls from 78% at 20 to 34% at 30, 16% at 40, 4.5% at 60 and 1.6% at 80. The delta rises from 0.84 shares per bond at 20 to 2.39 at 80, approaching the conversion ratio of 2.5.
Example 21.10 (What the credit link changes)
Take , the same 300-basis-point spread at today’s price. The hazard is 18.7% a year at a share price of 10 (Figure 21.2). The bond floor is now 78.1 at 20 and 90.4 at 80, where it was 83.2 at both. The convertible is worth 83.9 at 20 against 89.1 under the constant hazard, and 98.5 at 30 against 100.2. The delta is 1.55 shares per bond at 30 against 1.37, and 1.39 against 0.84 at 20. A falling share now also hurts the bond floor, so the convertible’s value falls faster. Below a share price of about 19 the gamma turns negative: at 15 and at 10. The convexity the desk thought it owned disappears where the credit takes over.
Example 21.12 (The hedge book)
At a share price of 30 the equity-to-credit model’s delta is 1.55 shares per bond. A 1 basis point widening of the issuer’s spread, at a fixed share price, costs the convertible 0.0167 per bond (1.67 per 100 basis points), about half the 0.0296 of the bond floor, since the conversion right cushions it. With a five-year risky annuity of 4.12, credit protection on 40.6% of the face offsets that sensitivity.