
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Busted convertible?

Definition 8.1 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · Hoofdstuk 8 — Convertible Arbitrage

A busted convertible is a convertible whose share price has fallen far below its conversion price, so that the conversion option is nearly worthless and the bond trades on its credit; its remaining equity sensitivity comes mostly from the link between the share price and the issuer’s default risk.
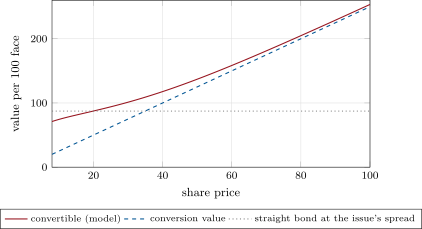
The chapter’s five-year convertible at issue, by share price: model value from Book 5’s pricer with an equity-to-credit hazard, conversion value (2.5 shares), and the straight bond discounted at the issue’s credit spread. At a share price of 19 and below the bond is worth less than the straight bond, as the hazard rises with the fall. Data: s2_convarb.profile.
Figure 8.1. The chapter’s five-year convertible at issue, by share price: model value from Book 5’s pricer with an equity-to-credit hazard, conversion value (2.5 shares), and the straight bond discounted at the issue’s credit spread. At a share price of 19 and below the bond is worth less than the straight bond, as the hazard rises with the fall. Data: s2_convarb.profile.
Lees in het hoofdstuk →