सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Conditional expectation क्या है?

Definition 1.2 Quantitative Methods · अध्याय 1 — Probability at Speed

Let XX be integrable and G⊆F\mathcal G \subseteq \mathcal F a sub-σ\sigma-algebra. The conditional expectation E[X∣G]\E[X \mid \mathcal G] is the almost surely unique G\mathcal G-measurable, integrable random variable YY with E[X1A]=E[Y1A]\E[X\mathbf 1_A] = \E[Y\mathbf 1_A] for every A∈GA \in \mathcal G. We write Et[X]=E[X∣Ft]\E_t[X] = \E[X \mid \mathcal F_t].

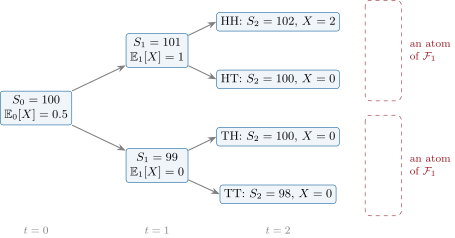
Conditional expectation as averaging over what is still unknown. F_1 splits the four outcomes into two atoms (dashed); _1[X] is the average of X on the atom reached, and _0[X] is the average of _1[X]: the tower rule. The three values 0.5 1 2 along the top path form a Doob martingale.
Figure 1.1. Conditional expectation as averaging over what is still unknown. F1\mathcal F_1 splits the four outcomes into two atoms (dashed); E1[X]\E_1[X] is the average of XX on the atom reached, and E0[X]\E_0[X] is the average of E1[X]\E_1[X]: the tower rule. The three values 0.5→1→20.5 \to 1 \to 2 along the top path form a Doob martingale.
अध्याय में पढ़ें →