All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Contango and backwardation?

Also known as: contango · backwardation

Definition 21.8 Markets I: The Ecosystem and Exchange-Traded Markets · Chapter 21 — Basis, Roll and Delivery

A futures curve is in contango when later expiries trade above nearer ones, and in backwardation when they trade below.
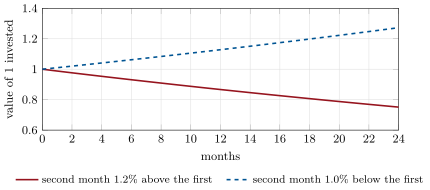

A long position rolled monthly for two years while the spot price never moves from 70. In contango it loses 25%; in backwardation it gains 27%. An investor who “bought oil” through futures bought the curve as well. Data: the tutorial’s simulation.
Figure 21.3. A long position rolled monthly for two years while the spot price never moves from 70. In contango it loses 25%; in backwardation it gains 27%. An investor who “bought oil” through futures bought the curve as well. Data: the tutorial’s simulation.
Read in context →