 Pelatih
Convertible arbitrage is the strategy of buying convertible bonds that trade cheap to a model’s value, selling the issuer’s shares short in the model’s delta and often buying credit protection, to earn the convertible’s convexity, its coupon net of the short’s cost, and the convergence of its price to value.
Contoh
Example 21.12 (The hedge book)
At a share price of 30 the equity-to-credit model’s delta is 1.55 shares per bond. A 1 basis point widening of the issuer’s spread, at a fixed share price, costs the convertible 0.0167 per bond (1.67 per 100 basis points), about half the 0.0296 of the bond floor, since the conversion right cushions it. With a five-year risky annuity of 4.12, credit protection on 40.6% of the face offsets that sensitivity.
Example 21.13 (Share down 20%, spread 300 basis points wider)
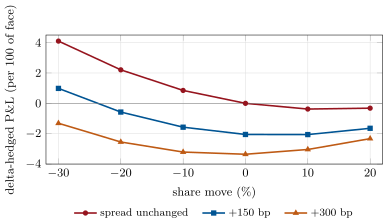
The share falls from 30 to 24, and the issuer’s spread at that price ends 300 basis points above today’s, a hazard of 10%. The convertible falls from 98.47 to 86.62, a loss of 11.84 per 100 of face. The short of 1.55 shares gains 9.30. The delta-hedged position loses 2.55 per 100 of face, 2.55 million on 100 million. Hedged with the constant-hazard model’s delta of 1.37 instead, it loses 4.38. The credit protection gains 4.47 in the same scenario and turns the loss into a gain of 1.93. The wider spread alone, with no move in the share, costs the delta-hedged position 3.35. The share move alone, with the spread held, earns it 2.21 of convexity (Figure 21.4).