 Coach
The convexity adjustment of a short-rate future is the difference between its implied rate and the forward rate for the same period.
उदाहरण
Example 8.11 (Five and ten years out)
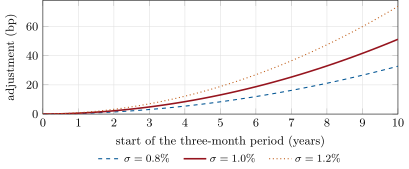
With a normal volatility of 1% a year, the three-month contract starting in five years carries basis points of adjustment; the one starting in ten years, 51.25. At the front it is negligible; at the back of the strip it is larger than a typical move in a day, and a curve built from futures without it is wrong (Figure 8.4).