
Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Convexity adjustment?

Definition 8.9 Markets II: Rates, FX and Credit · Capítulo 8 — Short-Term Interest-Rate Futures

The convexity adjustment of a short-rate future is the difference between its implied rate and the forward rate for the same period.
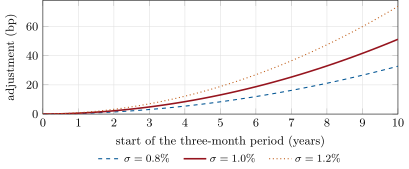
The Ho–Lee convexity adjustment of a three-month futures rate by the start of its period, for three volatilities. It grows with the square of the horizon and of the volatility: negligible for the first contracts, tens of basis points for the last. Data: the chapter’s tutorial.
Figure 8.4. The Ho–Lee convexity adjustment of a three-month futures rate by the start of its period, for three volatilities. It grows with the square of the horizon and of the volatility: negligible for the first contracts, tens of basis points for the last. Data: the chapter’s tutorial.

Exemplos

Example 8.11 (Five and ten years out)

With a normal volatility of 1% a year, the three-month contract starting in five years carries 12×0.012×5×5.25=13.1\frac12 \times 0.01^2 \times 5 \times 5.25 = 13.1 basis points of adjustment; the one starting in ten years, 51.25. At the front it is negligible; at the back of the strip it is larger than a typical move in a day, and a curve built from futures without it is wrong (Figure 8.4).

Ler no capítulo →