A convexity budget is the premium a manager is willing to spend on options to express views, whose most it can lose; spending it buys positions whose loss is known in advance and whose gain grows with the size of the move.
s2_macrobook.table. Coach
Entrar
Começar a ler
Quantitative Finance · Glossário
A convexity budget is the premium a manager is willing to spend on options to express views, whose most it can lose; spending it buys positions whose loss is known in advance and whose gain grows with the size of the move.
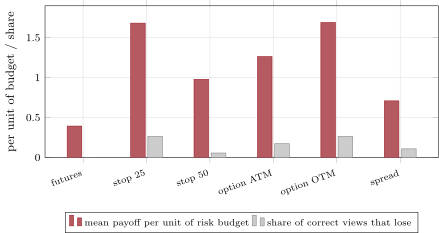
s2_macrobook.table.