المدرب
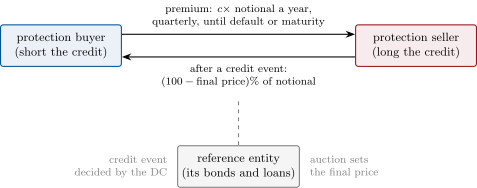
A credit default swap (CDS) is a bilateral contract in which the protection buyer pays a regular premium on a notional amount until maturity or until a credit event of a named borrower, the reference entity, whichever comes first; after a credit event the protection seller pays the buyer the notional times one minus the recovery value of the entity’s debt, fixed by settlement.