
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Credit default swap, protection buyer and seller, reference entity क्या है?

अन्य नाम: credit default swap · protection buyer · reference entity · protection seller

Definition 23.1 Markets II: Rates, FX and Credit · अध्याय 23 — Credit Default Swaps

A credit default swap (CDS) is a bilateral contract in which the protection buyer pays a regular premium on a notional amount until maturity or until a credit event of a named borrower, the reference entity, whichever comes first; after a credit event the protection seller pays the buyer the notional times one minus the recovery value of the entity’s debt, fixed by settlement.
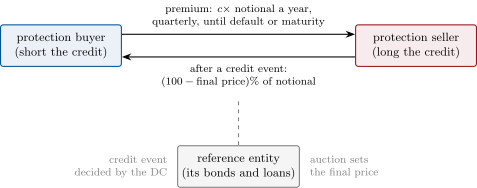
The cash flows of a credit default swap. The buyer pays a running premium until a credit event or maturity; after a credit event, determined by a committee, the seller pays the notional times one minus the price of the entity’s debt set by an auction. Schematic.
Figure 23.1. The cash flows of a credit default swap. The buyer pays a running premium until a credit event or maturity; after a credit event, determined by a committee, the seller pays the notional times one minus the price of the entity’s debt set by an auction. Schematic.
अध्याय में पढ़ें →