
All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Cross-validation?

Definition 16.7 Quantitative Methods · Chapter 16 — Linear Models under Stress

Cross-validation chooses a penalty by fitting on part of the data and measuring the prediction error on the rest, over several splits. With time series, every training set must precede its test set, with a gap (a purge) at least as long as the dependence between the targets, so that no information from the test period leaks into the fit.
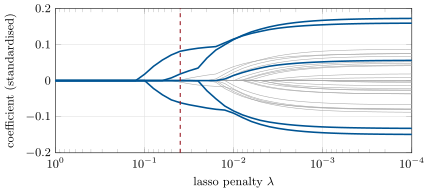
Lasso path of the thirty standardised predictors as the penalty falls from 1 to 10-4: the five true signals in blue, the twenty-five noise predictors in grey, and the cross-validated penalty 0.040 (dashed), where five coefficients are nonzero. Data: the chapter’s tutorial, seeded.
Figure 16.2. Lasso path of the thirty standardised predictors as the penalty falls from 1 to 10−410^{-4}: the five true signals in blue, the twenty-five noise predictors in grey, and the cross-validated penalty 0.040 (dashed), where five coefficients are nonzero. Data: the chapter’s tutorial, seeded.
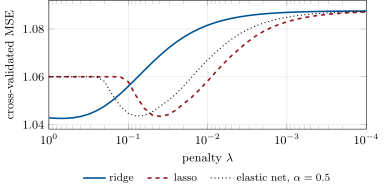
Time-ordered cross-validation error of the three penalised regressions against the penalty (five expanding folds with a five-day purge, on the first 1 500 days). Each curve has an interior minimum: too little penalty fits noise, too much discards signal. Data: the chapter’s tutorial, seeded.
Figure 16.3. Time-ordered cross-validation error of the three penalised regressions against the penalty (five expanding folds with a five-day purge, on the first 1 500 days). Each curve has an interior minimum: too little penalty fits noise, too much discards signal. Data: the chapter’s tutorial, seeded.
Read in context →