
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Cubic, natural and monotone splines, Runge phenomenon؟

يُعرف أيضًا باسم: cubic spline · natural cubic spline · monotone cubic interpolation · Runge phenomenon

Definition 28.5 Quantitative Methods · الفصل 28 — Transforms, Interpolation and Algorithmic Differentiation

A cubic spline through (xi,yi)(x_i, y_i) is a piecewise cubic with continuous first and second derivatives; a natural cubic spline has zero second derivative at both ends, and its second derivatives at the nodes solve a tridiagonal system. Monotone cubic interpolation chooses the node slopes of a piecewise cubic Hermite interpolant so that it is monotone wherever the data are. The Runge phenomenon (Runge, 1901) is the growth, near the ends of the interval, of the error of polynomial interpolation at equally spaced nodes as the degree increases.
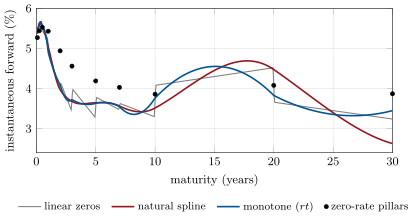
Instantaneous forward curves implied by three interpolations of the Treasury curve of 3 July 2023, with the pillar yields (treated as zero rates). Data: FRED series DGS1MO to DGS30 (Board of Governors of the Federal Reserve System, H.15).
Figure 28.2. Instantaneous forward curves implied by three interpolations of the Treasury curve of 3 July 2023, with the pillar yields (treated as zero rates). Data: FRED series DGS1MO to DGS30 (Board of Governors of the Federal Reserve System, H.15).
اقرأ في الفصل →