 Coach
A discount curve gives the present value of a cash flow paid under a given collateral agreement; a projection curve of an index gives its forward fixings, as , without being used to discount anything. The multi-curve framework values a swap by projecting each floating fixing on its index’s projection curve and discounting every cash flow on the discount curve of the trade’s collateral.
Exemples
Example 2.5 (A euro market)
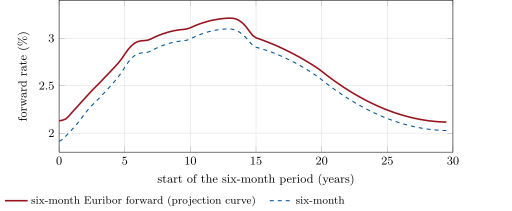
Take illustrative €STR swap rates from 1.95% at one year to 2.55% at ten and 2.60% at thirty, and six-month Euribor swap rates 20 basis points higher at one year, 15 at ten and 12 at thirty, with a six-month fixing of 2.13%. The projection curve reprices all ten Euribor instruments; by Proposition 2.2 the tenor basis is 20, 15 and 12 basis points at one, ten and thirty years. The forward basis, fixing by fixing (Figure 2.1), is 21.6 basis points on the first six-month period and 11.8 on the period starting in ten years: a par basis is an average of forward bases.
Example 2.6 (One swap, two frameworks)
A receiver of 3.50% against six-month Euribor for ten years on EUR 100 million, with the ten-year Euribor swap at 2.70%, is worth EUR 7 135 408 in the multi-curve framework and EUR 7 075 108 on a single curve built from the Euribor swaps, which discounts at the higher Euribor rates. Both frameworks agree on the par rate, 2.70%, because each is calibrated to it; they disagree by EUR 60 300 on an off-market swap.