 المدرب
A book has dollar neutrality when its long and short weights sum to zero, beta neutrality when its market beta is zero, and satisfies a factor-neutrality constraint when its exposure to a risk-model factor is zero. A name limit bounds each position’s weight; a liquidity constraint bounds it by a fraction of the stock’s average daily traded value relative to the book’s capital. A 130/30 portfolio is long 130% and short 30% of its capital: a long-only mandate given limited room to short.
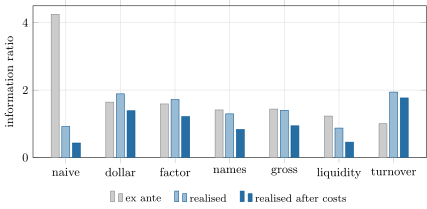
rs_portcons.summary.