
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Dollar, beta and factor neutrality; name limit; liquidity constraint; 130/30 portfolio?

Ook bekend als: dollar neutrality · beta neutrality · factor-neutrality constraint · name limit · liquidity constraint · 130/30 portfolio

Definition 25.4 Research Craft: Predictors, Backtests, Measurement, Portfolios · Hoofdstuk 25 — Portfolio Construction I

A book has dollar neutrality when its long and short weights sum to zero, beta neutrality when its market beta is zero, and satisfies a factor-neutrality constraint when its exposure to a risk-model factor is zero. A name limit bounds each position’s weight; a liquidity constraint bounds it by a fraction of the stock’s average daily traded value relative to the book’s capital. A 130/30 portfolio is long 130% and short 30% of its capital: a long-only mandate given limited room to short.
Information ratios of the hundred-name book as constraints are added (each label names the constraint added to those on its left), 95 monthly rebalances. Ex-ante ratios fall with every constraint; realised ones do not follow, and the turnover limit gives the best book after costs. Data: rs_portcons.summary.
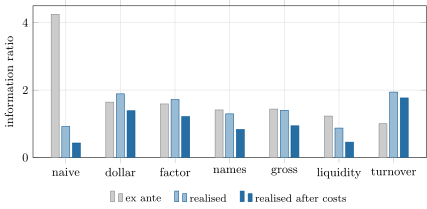
Figure 25.1. Information ratios of the hundred-name book as constraints are added (each label names the constraint added to those on its left), 95 monthly rebalances. Ex-ante ratios fall with every constraint; realised ones do not follow, and the turnover limit gives the best book after costs. Data: rs_portcons.summary.
Lees in het hoofdstuk →