Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Domain randomisation » ?

Definition 18.3 Machine Learning for Markets · Chapitre 18 — Reinforcement Learning for Execution and Market Making

Domain randomisation trains a policy on many versions of a simulator whose uncertain parameters are drawn at random for each episode, so that the policy works across them instead of exploiting one (Tobin and co-authors, 2017).
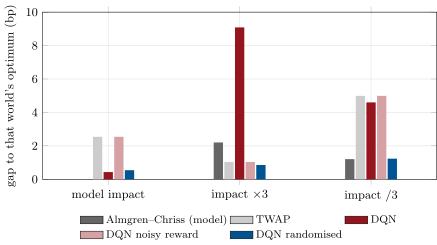
Each schedule’s objective minus the Almgren–Chriss optimum of the world it trades in (basis points). The closed form and the first DQN were built for the model’s impact; the randomised DQN was trained on impact drawn over a factor of three either way. Data: ml_rltrade.execution.
Figure 18.1. Each schedule’s objective minus the Almgren–Chriss optimum of the world it trades in (basis points). The closed form and the first DQN were built for the model’s impact; the randomised DQN was trained on impact drawn over a factor of three either way. Data: ml_rltrade.execution.
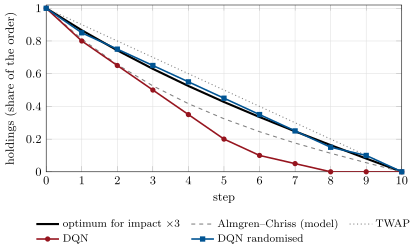
Holdings over the ten steps in the world with three times the model’s impact. Data: ml_rltrade.agents.
Figure 18.2. Holdings over the ten steps in the world with three times the model’s impact. Data: ml_rltrade.agents.
Lire dans le chapitre →