 Coach
The dual upper bound of a Bermudan option is for a martingale with and discounted exercise values ; it exceeds the price for every martingale and equals it for the martingale part of the value process. The Andersen–Broadie algorithm builds from a lower-bound policy by nested simulation, so that lower and upper bounds together give an interval for the price.
Exemples
Example 23.5 (The bias of too few inner paths)
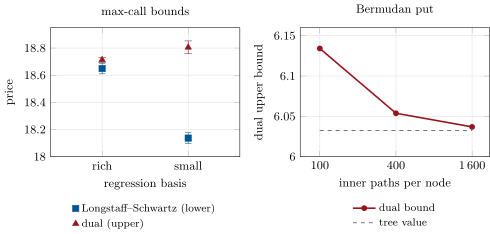
A one-year Bermudan put with ten exercise dates (spot and strike 100, 5%, 20%) is worth 6.0326 on chapter 6’s tree. Longstaff–Schwartz with a cubic basis gives 6.0325 (standard error 0.023). The dual bound on 1 000 outer paths is 6.134 with 100 inner paths per node, 6.054 with 400 and 6.037 with 1 600 (Figure 23.2, right).
Example 23.6 (A three-asset Bermudan max-call)
A call on the best of three independent shares (each at 100, strike 100, volatility 20%, dividend yield 10%, rate 5%), exercisable at nine dates over three years. The basis for the regression is a set of polynomials in the two largest prices, their product, the product of all three and the intrinsic value. With it, Longstaff–Schwartz on 200 000 fresh paths gives 18.649 (standard error 0.039), and the dual bound (1 000 outer paths, 1 000 inner) gives 18.713 (0.019). The gap is 0.064, 0.3% of the price. With a basis of only the largest price and its square, the lower bound falls to 18.137 and the upper rises to 18.805, a gap of 0.668, ten times wider (Figure 23.2, left).