 المدرب
The effective breadth of a set of forecasts is the number of independent forecasts that would give the same information ratio; bets with average pairwise correlation are worth about . The transfer coefficient of a portfolio is the cross-sectional correlation between its risk-adjusted active weights and the risk-adjusted forecasts .
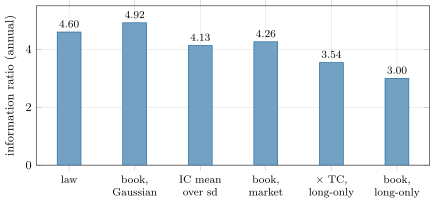
rs_forecast.law.